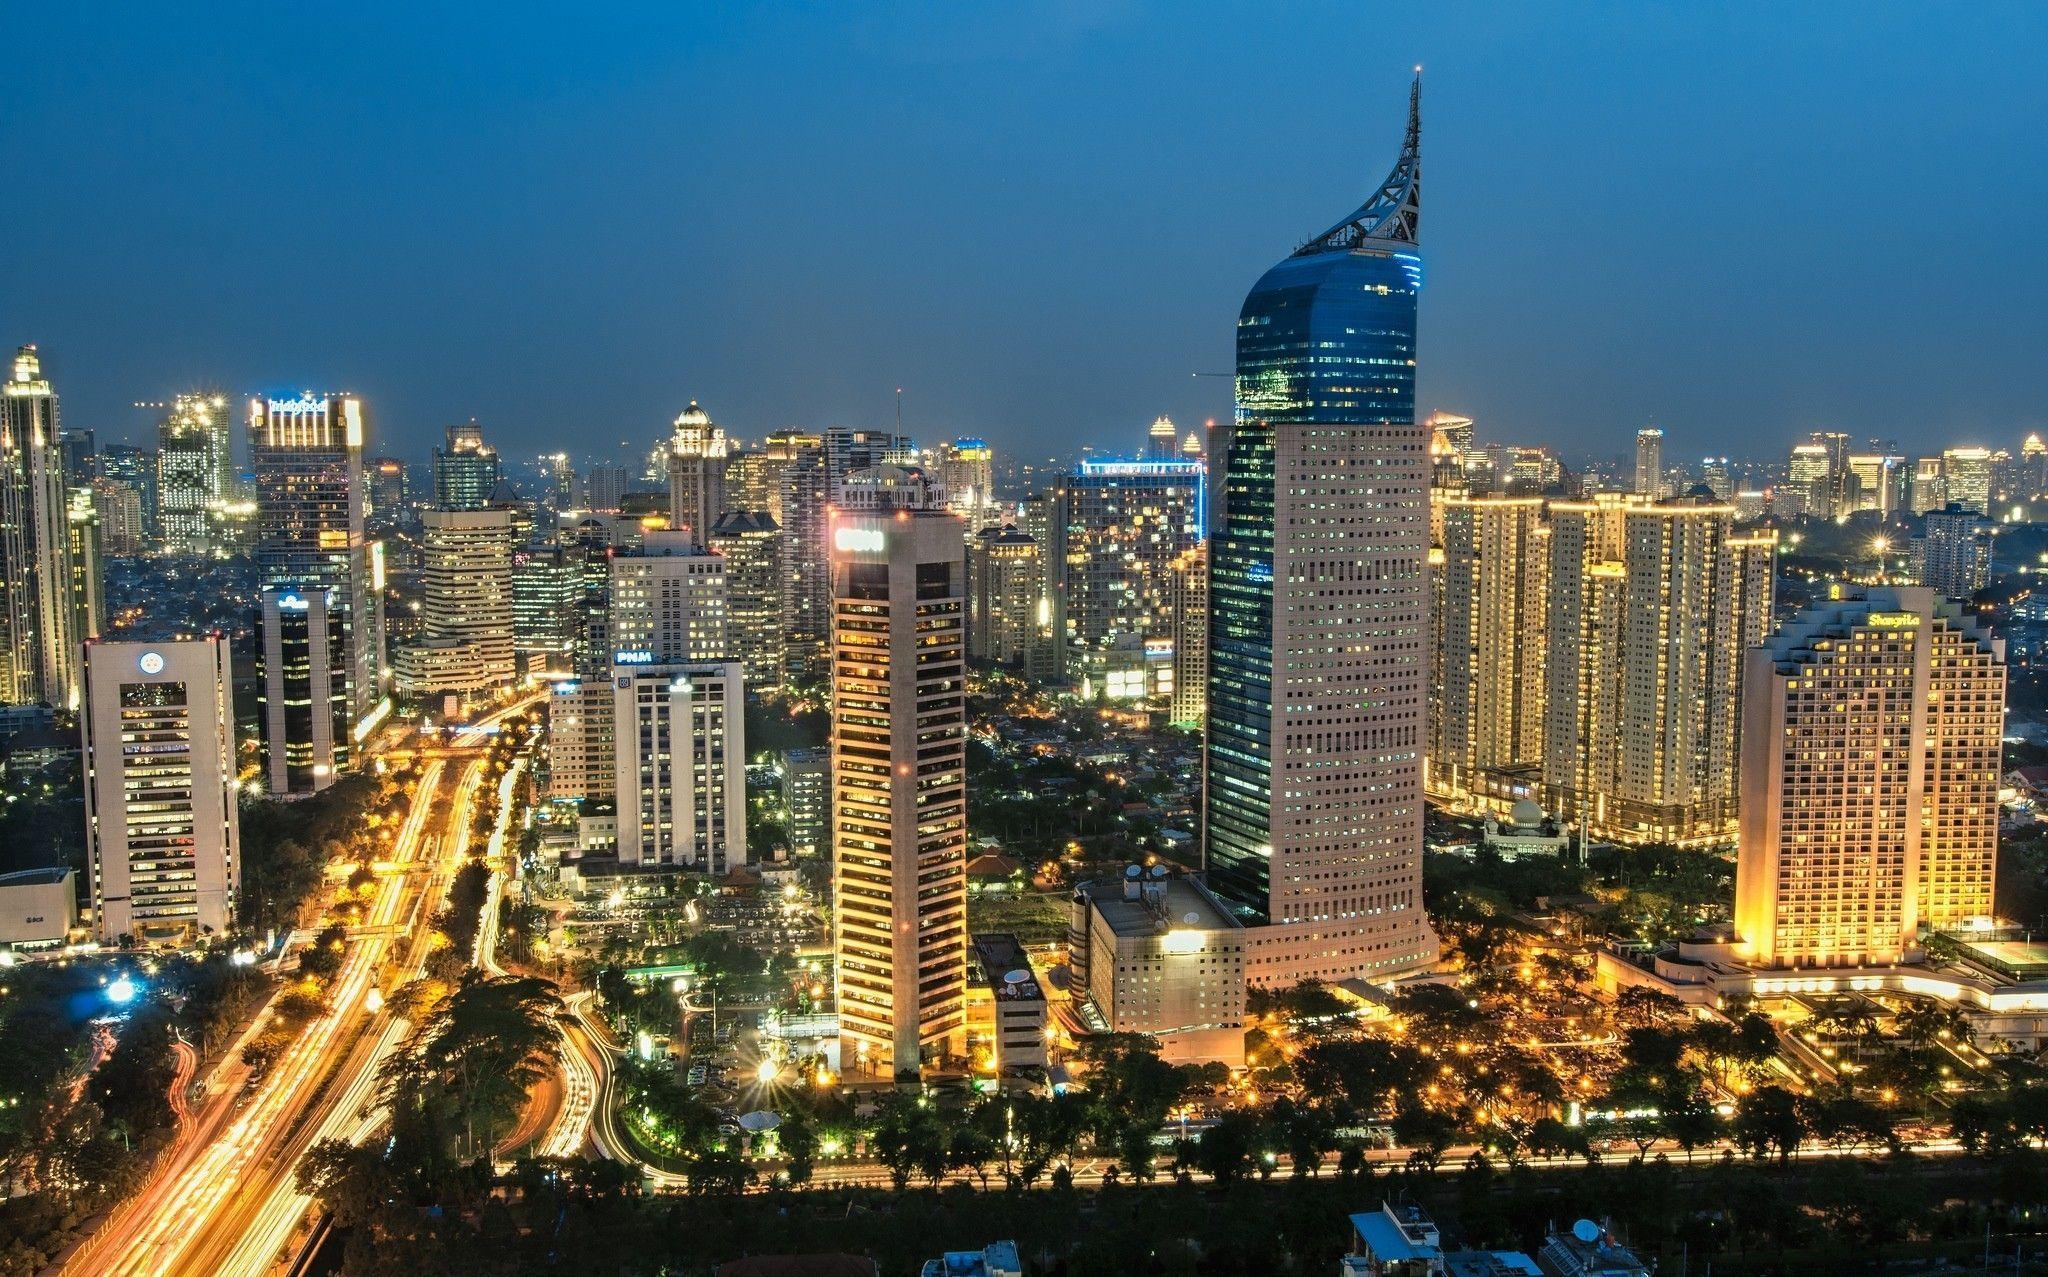
Indonesia's stock exchange is stripping roughly 300 tightly held companies—those with high shareholder concentration—out of the Jakarta Composite Index calculation to appease MSCI and stave off a catastrophic index reclassification. Yet purging thin stocks from the headline gauge does nothing to fix opaque ownership trails or restore the foreign capital that has already fled the market.
I have watched emerging equity markets convulse for thirty years, and the pattern in Jakarta feels painfully familiar. A market rides a wave of domestic enthusiasm and headline valuations while ignoring structural plumbing. Then an index provider pulls a thread, exposing thin liquidity and concentrated control, and suddenly every rulebook is rewritten in a panic.
Why Free Float Became Jakarta's Fault Line
A free float sounds like a dry technical metric until you try to exit a position during a sell-off. In plain terms, it is the share of a company's stock held by public investors and genuinely available to trade, rather than locked up with founders, controlling families, state entities, or insiders.
When free float is razor-thin, price discovery turns into theater. A small amount of buying or forced selling can whip a stock around because there simply are not enough shares changing hands on the open market. Worse, when ownership is concentrated behind layers of corporate vehicles, outside investors have a hard time knowing who actually pulls the strings or whether reported public floats are real.
For years, Indonesian listing rules allowed companies to operate with minimal public float. Regulators moved to tighten minimums and pushed toward a 15% benchmark after MSCI froze index changes in January 2026. The exchange also targeted high shareholder concentration stocks, defined under the framework where ten or fewer shareholders control 92.5% or more of a company's shares. Removing those names from the Jakarta Composite Index calculation—effective in early November 2026—changes the math of the benchmark. It does not magically create deep order books overnight.
What MSCI Actually Put on the Table
Index providers do not wake up and decide to blow up a major Southeast Asian equity market for sport. MSCI's warning shot in January 2026 froze additions, migrations, and upward adjustments for Indonesian securities while authorities scrambled to respond. Top officials at the exchange and financial regulator resigned amid a bruising market rout, and billions of dollars in foreign money walked out the door over the course of the year.
Then came the real shock in October 2026. Rather than merely floating a routine demotion to frontier market status, MSCI launched a formal consultation on reclassifying Indonesia from an Emerging Market to a Standalone Market, setting a feedback window through April 30, 2027, with a final ruling due by June 30, 2027.
| Classification Tier | What It Signals to Global Funds | Practical Impact on Market Access |
|---|---|---|
| Emerging Market | Broad institutional inclusion with standard EM benchmarks | Core allocation for global EM funds and ETFs, subject to investability screens |
| Frontier Market | Smaller, less liquid, or earlier-stage equity markets | Triggers forced exits by EM-mandated funds; smaller dedicated frontier pools |
| Standalone Market | Outside standard regional or EM/frontier benchmarks | Treated as a bespoke market; many passive and mandate-bound funds cannot hold it |
Standalone status is a harsh label in institutional finance. Many global equity mandates simply are not built to buy or hold standalone markets easily, which is why even the prospect of the move triggered sharp drops in Indonesian equities and pressure on the rupiah.
Removing Stocks From the Index Is Not Market Reform
Stripping tightly held stocks out of the Jakarta Composite Index is an accounting adjustment, not a cure for market opacity. The underlying shares can still trade on the exchange. Their price swings just stop distorting the headline index number.
That creates a side effect traders should watch closely. Once high-concentration stocks are excluded from the index calculation, their weight gets redistributed across the remaining constituents—predominantly large, liquid names, including major banks and telecoms. Meanwhile, MSCI's own November 2026 review trimmed Indonesian representation further, removing Barito Pacific from the Global Standard Indexes and shifting Bumi Resources Minerals down to small cap, leaving only seven Indonesian names in the main Global Standard gauge ahead of the end-of-November implementation.
Concentrating index weight into fewer big stocks makes the benchmark cleaner on paper. It also means passive flows and index rebalancing hit those remaining liquid heavyweights harder.
Index math can hide illiquidity in a headline number, but global asset managers judge a market by whether they can get in, get out, and trust the ownership disclosures.
The Overlooked Reality of Enforcement and Ownership Trails
Most market commentary stops at free-float percentages and index weights. That misses the harder part of the problem: beneficial ownership and day-to-day enforcement.
Suppose a listed company reports a 15% public float on paper, yet several seemingly separate accounts or holding entities act in concert behind the scenes. Raising a headline threshold on a spreadsheet does not automatically expose hidden alliances. MSCI has noted that market participants want consistent execution across the broader market—not just around top index names—alongside clearer ownership visibility and reliable English-language disclosures for international investors.
There is also a tension between speed and credibility. Regulators have rushed out rule changes, raised fines, and adjusted trading limits in response to market stress. Announcements are easy. Proving over six to eight months of real trading that surveillance sticks, penalties bite, and ownership data holds up under scrutiny is much harder.
Why Some Critics Argue the Purge Goes Too Far
Not every domestic market participant views aggressive exclusions as a free lunch. Some analysts and local market voices have argued that abrupt index removals and tighter rules can penalize companies that are trying to adjust, or dampen domestic momentum at a moment when sentiment is already fragile.
Consider a hypothetical mid-sized manufacturer with a founder holding 88% of the shares and a handful of loyal local institutions holding another 6%. Even if the business has solid cash flow and pays steady dividends, concentrated ownership leaves little daily trading volume. Purging such a stock from the index calculation spares the benchmark from artificial price jumps, yet it gives the controlling shareholder even less immediate market pressure to broaden public ownership unless listing and enforcement rules force the issue.
That trade-off sits right at the center of Jakarta's dilemma. A market built around family conglomerates and concentrated control cannot become an institutional trading hub overnight without bruising some incumbents.
What Institutional Investors Will Actually Watch Next
Between now and MSCI's deadline of June 30, 2027, foreign institutions will not grade Jakarta on press conferences or one-off index tweaks. They will look for concrete proof on three fronts:
- Consistent enforcement: Whether exchange and regulatory rules on free float, disclosure accuracy, and market abuse are applied evenly without quiet exemptions.
- Ownership clarity: Whether data on major shareholders and affiliated holdings gives global funds an accurate picture of true tradable supply.
- Sustained liquidity: Whether trading depth and foreign participation stabilize rather than evaporating further ahead of the 2027 decision.
Until those boxes are checked in live trading, purging tightly held stocks from the Jakarta Composite Index is a tourniquet on a deeper structural wound.