Informal family housing arrangements fail in court not because judges lack sympathy for aging parents, but because trust substitutes for enforceable legal instruments at the exact moment incentives shift. When an older homeowner transfers title to a son-in-law or other relative based on an alleged verbal promise of lifetime occupancy, the transaction creates an immediate structural asymmetry: the new owner acquires full marketable title and legal control, while the prior owner retains only an unwritten expectation. This analysis breaks down the structural mechanics behind failed verbal life-estate claims, maps the legal and economic failure modes of family real estate transfers, and provides a step-by-step protocol for protecting housing security without relying on unrecorded promises.
The Structural Asymmetry of Informal Family Transfers
Most disputes over family home sales arise from a false equivalence between relational trust and legal rights. Within a functioning household or close kinship network, people routinely operate on implied reciprocity. A parent helps a child or son-in-law buy or take over a property under the assumption that goodwill will govern future decisions. Yet real estate law does not enforce goodwill; it enforces recorded property interests, statutory formalities, and evidentiary standards.
To understand why these arrangements collapse, separate the known facts of a typical dispute from educated hypotheses about how parties arrive there. The known legal mechanism in property disputes is straightforward: once fee simple title transfers to a buyer and no recorded life estate, lease, or enforceable written agreement restricts possession, the titled owner generally holds superior legal rights to manage, encumber, or recover possession of the property, subject to state-specific statutes and equitable doctrines. An educated hypothesis about human decision-making explains why parties skip formal documentation in the first place: family members often view formal legal instruments as expressions of distrust or unnecessary friction during what feels like a cooperative rescue, estate simplification, or tax-adjacent transfer.
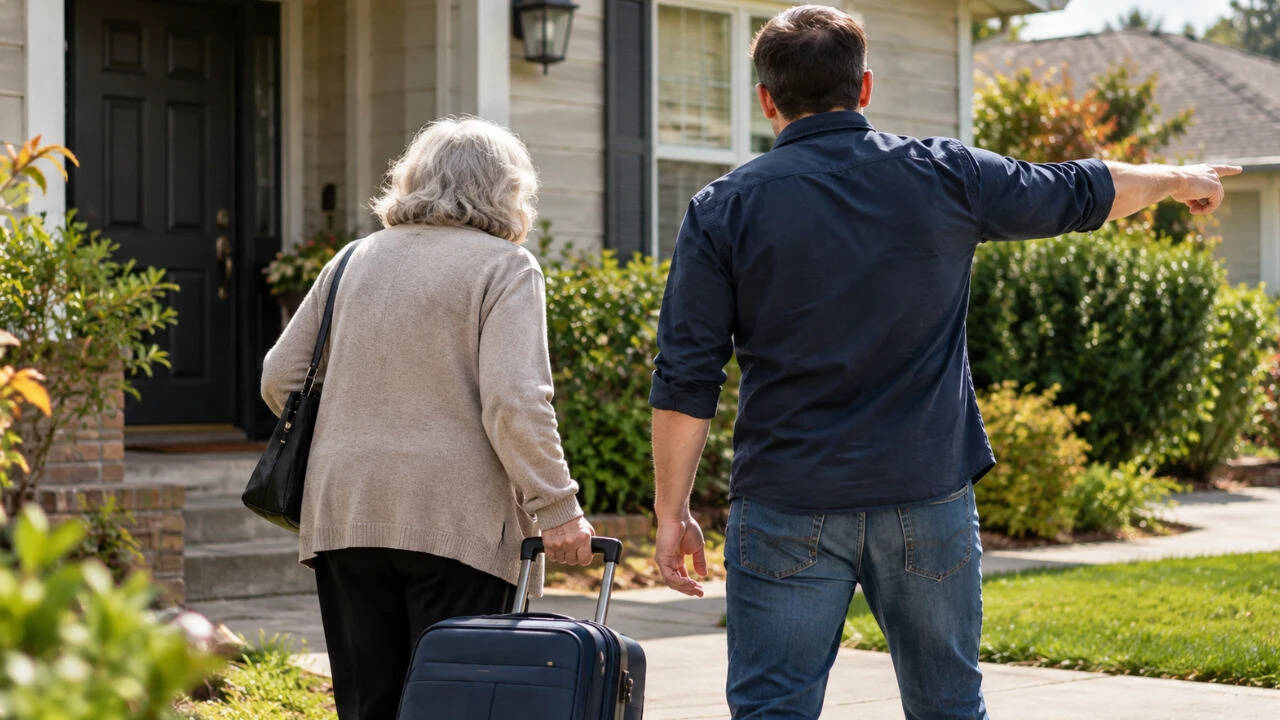
Consider a concrete structural pattern rather than a fictional story. Suppose an older homeowner sells or deeds a residence to a son-in-law for below-market value, nominal consideration, or a promise to cover ongoing expenses and allow lifelong residence. Years later, marriage dynamics change, financial pressures mount on the titled owner, or disagreements erupt over maintenance, caregiving, or household control. At that inflection point, the informal understanding is tested against formal property rules. What felt like a permanent arrangement under family norms turns out to be legally fragile because the underlying right to stay for life was never perfected as a durable property interest.
Three structural variables govern how vulnerable an informal family housing deal becomes:
- Title versus possession: Holding physical occupancy or having once owned the house does not equal holding a legally protected right to remain indefinitely.
- Consideration and documentation: Below-market transfers, family discounts, or informal payment arrangements often blur whether a transaction was a commercial sale, a gift, an equity-release arrangement, or a loan repayment.
- Change of circumstance: Divorce within the family, death of an intermediary spouse, refinancing, sale to a third party, or care transitions alter the economic calculus of the titled owner.
The Three Failure Modes of Unwritten Lifetime Occupancy Claims
When a homeowner claims a relative promised lifetime occupancy after a property transfer, the dispute typically breaks down across three distinct mechanisms: the Statute of Frauds, evidentiary standards, and incentive divergence.
1. The Statute of Frauds and Property Formalities
Real estate interests that endure—such as a life estate or long-term right of occupancy—generally implicate the Statute of Frauds across U.S. jurisdictions, including Oregon. The core rule exists to prevent fraud and perjury in high-value, long-duration land claims by requiring agreements transferring or creating interests in real property to be in writing and signed by the party to be charged.
A verbal promise to let someone live in a house "for life" sits on a fault line. Courts distinguish between a revocable license (permission to stay that may be revoked) and a durable property interest or enforceable contract to convey or burden land. Without a writing that clearly defines the scope, duration, and terms of occupancy—or a properly executed and recorded life estate deed—a claimant faces a steep statutory barrier.
Equitable exceptions such as part performance or promissory estoppel exist in many jurisdictions, yet they do not operate as automatic overrides. Courts scrutinize whether the occupant's actions are unequivocally referable to the alleged agreement rather than explainable by ordinary family living, rent-free housing, or shared household expenses. Paying utilities, doing yardwork, or continuing to live in a familiar home often fails to persuade a court that an enforceable lifetime property right was created.
2. Evidentiary Asymmetry Over Time
Family promises are rarely witnessed by neutral third parties or reduced to unambiguous terms at the kitchen table. Even when a conversation occurred, memories diverge years later when money and control are at stake. One party may recall a binding guarantee of lifetime shelter; the other may recall a casual assurance that "you'll always have a place here" contingent on harmony, affordability, or household norms.
This creates an evidentiary bottleneck. Courts adjudicate disputes based on admissible evidence, documents, financial trails, and credibility determinations—not on what felt obvious inside the family. When the written record shows an outright transfer of title and silence regarding a life estate, the burden of proof weighs heavily against the person asserting the unwritten restriction.
3. Incentive Divergence and Principal-Agent Friction
In agency theory, a principal delegates authority or assets to an agent whose incentives may diverge over time. In a family property transfer, the older seller often acts as a de facto principal relying on the younger titleholder's ongoing loyalty. Initially, their interests can look aligned: the family keeps the house, equity may be unlocked or preserved, and caregiving or bill-paying support may seem seamless.
Over time, incentives drift. The titled owner bears property tax, insurance, repair, and mortgage obligations, or wants to tap home equity through a loan or sale. If the family relationship fractures—especially in an in-law arrangement where marital stability acts as an unpriced bridge—the titled owner's financial and personal incentives can decouple completely from the occupant's need for housing security. Without a legally binding encumbrance on the title, the occupant has little leverage once goodwill erodes.
Why Informal Deals Look Attractive Before They Fail
Informal family transfers persist because they solve short-term friction while hiding long-term tail risk. Understanding why smart, well-meaning people enter these arrangements helps diagnose where the analysis in typical news coverage stops short.
Standard coverage of family property disputes usually frames the story as a binary clash between a sympathetic elder and an ungrateful relative. That framing captures the human drama, yet it misses the underlying system mechanics:
- Transaction cost avoidance: Hiring a real estate attorney, drafting a life estate deed or occupancy agreement, and recording instruments requires upfront money and coordination. Families often treat legal fees as waste when dealing with kin.
- Illusion of permanence: People project current family harmony forward indefinitely. They treat emotional closeness as a substitute for legal enforceability.
- Tax and benefit ambiguity: Homeowners sometimes transfer property to relatives while thinking about estate planning, probate avoidance, Medicaid look-back rules, or property tax assessments. Improvised transfers frequently create unintended tax or eligibility consequences without securing the seller's own housing.
- Role confusion: A son-in-law or adult child may be treated simultaneously as a trusted family member, a financial savior, and a property manager, blurring who holds authority over decisions like repairs, guests, or eventual sale.
This creates a classic tail-risk trap: nine out of ten informal arrangements may never end up in court, so participants underestimate the severity of the tenth case. When a dispute does erupt, the stakes are catastrophic—losing not just money, but shelter, stability, and family ties simultaneously.
How Courts Evaluate Competing Claims Without Rewriting Deals
A common misconception in housing disputes is that courts exist to "do what is fair" in a broad moral sense. In practice, courts operate within strict doctrinal boundaries so that property titles across the broader economy remain predictable and marketable. If judges routinely enforced vague, unrecorded family promises against clear property titles, real estate ownership and lending would lose certainty.
When evaluating a claim that a buyer promised lifetime occupancy after a home sale, legal analysis typically probes several operational questions:
- What did the deed and closing paperwork actually say? An unconditional warranty or quitclaim deed transferring fee simple interest sets the baseline legal posture.
- Was there a separate written agreement? Emails, texts, side letters, or contracts can sometimes bear on intent, though formal property formalities still govern whether a real property interest was validly created.
- How were expenses allocated? Who paid property taxes, insurance, principal, interest, and major capital repairs? Consistent payment patterns matter, though they do not automatically convert occupancy into a life estate.
- Did reliance cause an irreversible change? Courts look closely at whether the occupant gave up concrete legal or financial rights—such as selling another property or forfeiting a binding claim—specifically in reliance on a clear promise.
Even when a court sympathizes with an older adult's predicament, legal remedies are constrained by the record before the judge. Oral assertions of a lifetime promise rarely overcome clear title documents on their own.
Step-by-Step Protocol for Structuring Safe Family Housing Transfers
Anyone considering selling, gifting, or transferring a home to a family member—or buying a relative's home with an understanding that the seller will stay—should treat the transaction like a high-stakes contract governed by formal rules, even if family trust is high.
Step 1: Define the Housing Right Explicitly Before Transferring Title
Decide in plain, concrete terms what the seller's or occupant's housing right is supposed to be. "Stay for life" is too vague in practice unless paired with operational details. Clarify:
- Whether the person holds a life estate (a property interest during life) or a contractual right of occupancy/lease with defined terms.
- Whether occupancy is rent-free, tied to specific expense contributions, or conditioned on anything.
- Who controls major decisions such as remodeling, refinancing, insurance, or selling the property.
Step 2: Use Proper Legal Instruments and Record What Must Be Recorded
Work with a licensed real estate or elder law attorney in the state where the property sits to draft instruments that match the agreed structure rather than improvising from templates or verbal assurances. Depending on the goal and state law, options may include a deed reserving a life estate, a separate written occupancy agreement, or other formal structures. Ensure proper execution, notarization, and recording where required so third parties and future disputes cannot ignore the interest.
Step 3: Separate Emotional Trust From Financial and Legal Protections
Good family relationships do not need weak contracts; in fact, clear written terms protect relationships by preventing misunderstandings before stress hits. Both sides should understand worst-case scenarios—such as divorce between spouses, death of the connecting family member, disability, job loss, or disagreements over home maintenance—before money or title changes hands.
Step 4: Audit Downstream Financial, Tax, and Eligibility Effects
Before signing anything, check how transferring title or creating a life estate affects property taxes, capital gains considerations, mortgage due-on-sale clauses, homeowners insurance, and long-term care or government benefit rules. A transfer that solves one problem can trigger another if analyzed in isolation.
Step 5: Maintain Clean Paper Trails for Every Dollar and Decision
Keep organized records of appraisals or valuation basis, payments made, tax and insurance bills, repair contributions, and written agreements. If a dispute ever arises, documentary clarity is vastly superior to competing recollections of private conversations.
Limitations and Edge Cases of Formal Planning
Formalizing a family housing agreement reduces legal ambiguity, but it is not a cure-all. Every legal structure carries trade-offs and edge cases that practitioners must weigh upfront.
First, legal costs and complexity are real. Drafting tailored property documents, checking title, and coordinating legal advice across jurisdictions or family members takes time and money. For modest estates or urgent transitions, families sometimes face real budget constraints.
Second, a life estate or occupancy right creates friction if circumstances change. If an older adult later needs assisted living or moves to another state, a life estate can complicate selling or leasing the property unless all interest holders cooperate and structure consent terms carefully. Conversely, if a titled owner wants to sell or refinance, a recorded life estate restricts unilateral action—which is precisely why reluctant buyers sometimes resist it.
Third, no contract eliminates interpersonal conflict. Even when legal rights are clear on paper, enforcing rights against a relative or in-law is emotionally painful, slow, and expensive. Legal structure sets the boundaries and leverage; it cannot manufacture healthy family behavior.
Strategic Recommendation
If you are structuring a family home sale where the seller plans to stay, do not transfer fee simple title in exchange for an unwritten promise of lifetime occupancy—either execute and record a formal, attorney-drafted legal right tied to the property or keep the arrangement structured through explicit written terms before closing. Treat informal assurances as non-binding until reduced to enforceable legal form, verify how the structure interacts with local property law and household finances, and put the rules in writing while everyone is still on the same side.