Two governments are staring each other down over a $12.4 million bill, and nobody wants to blink first.
When the Federation of Sovereign Indigenous Nations announced legal action against Ottawa over a disputed $12.4 million repayment demand, the headline made it sound like a straightforward billing dispute. It isn't. What started as a forensic audit by KPMG looking into federal dollars spent between April 1, 2019, and March 31, 2024, has turned into a high-stakes fight over pandemic emergency rules, shifting federal goalposts, and how Ottawa audits Indigenous organizations.
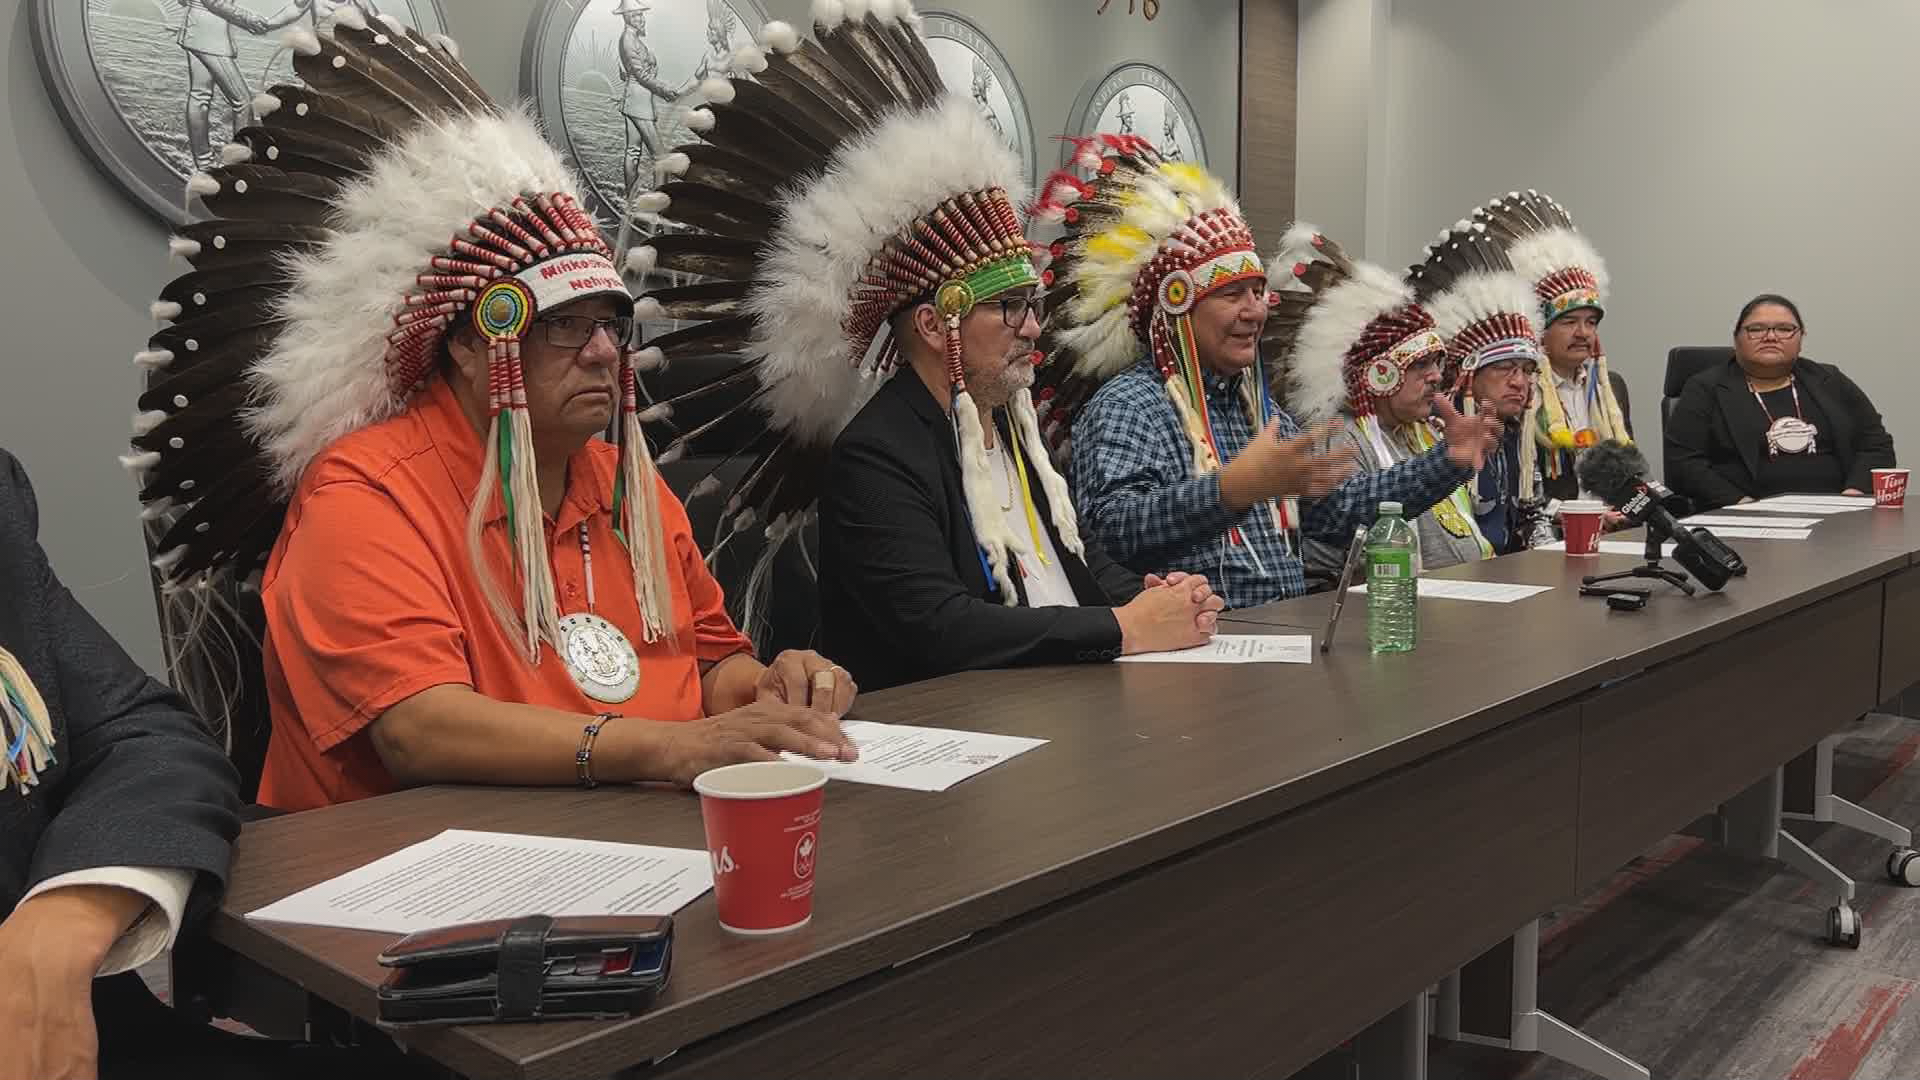
For readers trying to make sense of the standoff, the bottom line is clear. Indigenous Services Canada reduced an earlier repayment ask of roughly $28.7 million down to about $12.4 million, set a November 13, 2026 deadline for repayment to the Receiver General of Canada, and signaled plans to file a statement of claim to recover the money. The FSIN, which represents 74 First Nations in Saskatchewan, says the numbers don't hold up under independent scrutiny and refuses to simply hand over the cash.
How the FSIN Audit Dispute Escalated From Millions to Court
Audit fights rarely start at the courthouse. Usually, they begin in spreadsheets, policy manuals, and tense back-and-forth emails between bureaucrats and finance teams.
In this case, the KPMG forensic audit originally flagged roughly $34 million in questionable, ineligible, or unsupported transactions across the 2019 to 2024 window. Much of that scrutiny zeroed in on emergency COVID-19 response spending—including personal protective equipment procurement—alongside travel expenses, administrative fees, and payments tied to a former employee.
At first glance, seeing "$34 million" attached to a forensic audit makes people assume the worst. Anyone who has worked inside public procurement or emergency grant administration knows reality is rarely that neat.
During early COVID-19 waves, federal agencies pushed money out fast because supply chains were broken and communities needed protective gear immediately. Rules shifted on the fly. Documentation practices that look sloppy on paper five years later often happened in chaotic emergency rooms, band offices, and warehouses where getting masks and sanitizers out the door took priority over filing three extra forms.
Even after negotiations knocked the demand down from roughly $28.7 million to around $12.4 million, friction didn't disappear. FSIN leadership argued that Ottawa added items back into the tally despite supporting records—including delivery sign-offs from chiefs and feedback from Indigenous Services Canada staff. Meanwhile, Ottawa held firm that federal accountability rules require clear proof of eligible spending and signaled that unpaid balances could be pursued through a statement of claim or set off against future funding.
What Both Sides Actually Argue
Strip away the press releases, and each side is defending a different kind of risk.
Ottawa's position rests on taxpayer accountability and grant compliance. When federal departments distribute public funds, auditors look for paper trails matching strict eligibility criteria. If receipts are missing, coding is inconsistent, or expenses don't fit program terms, departments face pressure from auditors general and parliamentary committees to recover the money.
The FSIN's position rests on fairness, documentation, and policy clarity. Chief Bobby Cameron and FSIN leadership have maintained that expenses were handled properly, pointing to delivery confirmations and arguing that a chunk of the remaining dispute—around $4.4 million tied largely to administrative fees—lacks clear supporting policy from Ottawa. From the FSIN's vantage point, demanding clawbacks over vague rules or reversed positions turns an audit into a moving target.
What Most Coverage Misses About Federal Clawbacks
Short news clips tend to treat a repayment demand like a bounced check. Just pay the balance and move on.
In government funding disputes, it doesn't work like that. Once a department formalizes a repayment demand, the legal and operational stakes widen quickly.
First, funding set-offs hurt ongoing operations. When a federal department warns that it can use money owed to an organization as a "set-off" against a formalized debt, every future transfer feels precarious. Even if a dispute centers on past pandemic procurement, the cash-flow squeeze hits current programs and staff.
Second, court discovery cuts both ways. Heading to court over a statement of claim isn't just about whether one receipt is missing. Litigation opens up internal correspondence, audit methodology, and decision-making records. Chief Cameron has pointedly suggested that looking closely at how Ottawa authorized emergency funds and handled oversight during the pandemic could expose uncomfortable questions for federal decision-makers too.
Third, a reduction from $28.7 million to $12.4 million proves negotiations moved the needle—and left gray zones behind. If every dollar of the initial demand had been rock-solid, the number wouldn't have dropped by more than half. Yet the fact that over $12 million still remains contested shows how hard it is to reconcile emergency-era spending with peacetime audit standards.
When emergency rules collide with standard audit checklists years later, almost everyone finds something to fault—and almost nobody agrees on where the line sits.
Why This Matters Beyond Saskatchewan
You don't have to live in Saskatchewan to care how this plays out.
Across Canada, Indigenous organizations, municipalities, nonprofits, and contractors all navigate federal contribution agreements. Those agreements routinely come with dense terms, shifting interpretations, and delayed guidance. When an audit happens years after money was spent, institutional memory fades—staff leave, guidelines get updated, and proving compliance becomes an uphill battle.
Honestly, there's a bigger trust problem here too. Reconciliation and cooperative governance require predictability. When a partner organization feels that rules are applied inconsistently—or that promises made during negotiations get walked back—credibility takes a hit on both sides. At the same time, public money really does need clear guardrails so funds reach intended communities without waste or confusion.
Neither side gets a free pass on that tension. Ottawa has every right to enforce financial controls, and Indigenous organizations have every right to demand transparent rules, accurate accounting, and an impartial review rather than unilateral pressure.
Practical Steps for Anyone Tracking or Managing Grant Audits
If you run a non-profit, manage public grants, or simply want to follow how this case unfolds without getting swept up in spin, a few practical habits make a big difference.
- Read primary filings and official statements rather than headlines alone. Watch for actual court pleadings, statement of claim details, and formal responses rather than relying on short summaries.
- Separate disputed categories from raw totals. Look at how much of a figure stems from missing receipts versus policy disagreements over administrative fees or eligibility definitions.
- Keep contemporaneous sign-offs and policy versions. If you administer public funds, archive the exact program guidelines in effect when spending occurred, along with delivery logs and written approvals from program leads.
- Document verbal assurances in writing. Any time agency staff give guidance or indicate a path forward during an audit review, follow up with a clear written summary so nothing gets lost later.
Courts take their time, and legal battles over public funds rarely end with a neat knockout punch. Watching how the evidence and legal arguments hold up once formal court records are tested will tell the real story.